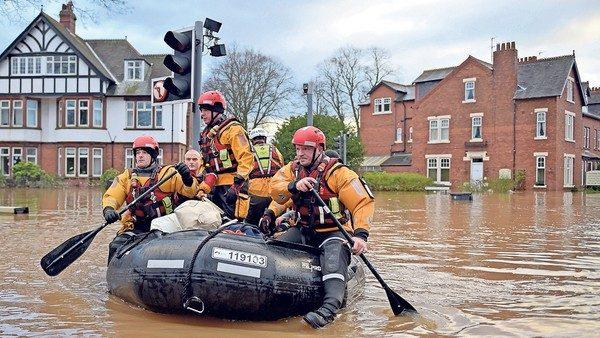
Please excuse the outrageous pun. It was frankly difficult to come up with a title not involving one. Once again in recent weeks we have been reminded of the dangers and almost inevitable regularity of flooding to large swathes of the UK. Rain.
by it’s very nature is indiscriminate where flood defences are concerned and so whilst they may be largely effective at diverting a swelling river water must go somewhere and often significant rainfall will cause issues concerning surface water. This is perhaps why we are seeing flooding to areas not in the immediate vicinity of a water course. Historically the Environment Agency have mapped areas where flooding is likely to arise from a burst river or similar water course. It is only in recent times that more attention has been placed on areas where surface water is an issue (or a likely issue) along with things such as chalk springs and the like. This more advanced flood modelling monitors and predicts the likelihood of flash-flooding alongside those more obvious risks.
The Sunday Times recently reported of a reader who had been ‘hit by a 1,300%’ insurance increase for a home that had never flooded. Clearly a shocking headline and story however the journalist, not being an insurance professional, does not quite hit the point on this one, rather using this case as a headline to (quite rightly) highlight a wider issue. The price rise in question is the attitude of a single insurer and that insurer, not the market as a whole. This was not a mid-term charge but a renewal offer which of course the reader was not obliged to take on. The insurer in question had recently taken on some new flood mapping and had decided clearly that this particular area was ‘not for them’ and whilst offering renewal was clearly suggesting, through their price, that this was what it would cost for them to take the risk. I am also uncomfortable with the phrase ‘which had never flooded’. The experienced driver in the new Ferrari (other performance cars are available) might never have been involved in an incident but this doesn’t mean that there is no future risk. Insurers, whilst taking into account the past, will always base their rates on what they predict might happen in the future. I am pleased to report that the reader in question, having consulted an Insurance Broker (what a wise man) he managed to obtain a premium much closer to what had previously been paid. This I think is the key take home point from this specific story – insurers will all have flood mapping, some will be more willing to take on risks than others and so consulting an insurance Broker and not relying on straight-forward yes/no online or direct markets is key.
In the wake of the recent Cumbria flooding the Government decreed that there would be some £50,000 of funds available to assist with households able to claim up to £5,000 of it. It wasn’t immediately clear how this could be used but guidance from the Government and reports in the media state this isn’t as a replacement for insurance claims but as a fund to assist in personal flood defences or raising internal plug sockets to safer levels and the like.
There is also a system akin to the Governments Pool-re Terrorism arrangement whereby insurance policies contribute to a central flood insurance fund held by the government. This new arrangement will place a cap on the premium charged by insurers for the risk of flood (within the overall premium) at between £210 and £1200 depending on the type of property and it’s individual risk to flood. At present this ‘Flood-re’ arrangement only applies to residential properties. Commercial Properties and Buy to Let residential properties will still be subject to insurers ‘open’ flood rates – in this case again, I’d stress the requirement for a Broker to assess the risk and approach the wider market.
Need any more information on anything outlined above? Call us on 01753 882222. For more information on the risk of flood in general visit the environment agency website or the National Flood Forum – www.nationalfloodforum.org.uk.
Fairweather Insurance
01753 882222
FT article on Cumbria Flooding Grants – https://www.ft.com/cms/s/0/0e6cf11e-9e9a-11e5-b45d-4812f209f861.html#axzz3uTUIhEFA
BBC Article on Flooding – https://www.bbc.co.uk/news/uk-england-35086905